Baht to euro: how the exchange rate changes your condo price
A Thai condo has one price, in baht. What it costs you in euros, pounds or dollars depends on the exchange rate on the day each payment leaves your account. Here is how that works, how we convert prices on this site and what to ask your bank.
The price of a Thai condo is fixed in Thai baht (THB), and that is the amount in your contract. The number of euros you pay is not fixed. It depends on the exchange rate on each day you send money, and on what your bank charges for the conversion. For a purchase paid in stages over two years, that difference adds up.
This guide explains the mechanism without forecasting the rate. It covers how we convert prices on this site, what currency risk looks like on a staged schedule, which currency to send and what to ask your bank. The examples use euros, but the same logic holds for pounds, dollars or any other currency.
Prices are fixed in baht; euros and dollars are a guide
The developer sets prices in baht. Every euro or dollar figure you see on this site is an estimate, marked “about”, with the date of the exchange rate used.
For example, prices at The Astra Samui start from THB 3,700,000 (about €98,000, NBP average rate of 23 October 2026). The baht figure is binding. The euro figure next to it shows the order of magnitude on that date and nothing more. On the prices page you can switch the estimates between euros and US dollars.
The same applies to other costs. Fees at the Land Office are set in baht too. At this project, according to the developer: Transfer fee: 2%, split equally (1% paid by the buyer). The condo buying costs guide lists what comes on top of the price.
How we convert prices on this site
We do not invent our own rate. The site takes the average exchange rate from table A of the National Bank of Poland (NBP), which includes the Thai baht, the euro and the US dollar against the Polish zloty. A baht-to-euro rate is then a cross rate: the zloty value of one baht divided by the zloty value of one euro.
Why the NBP? It publishes a dated official average every working day, and this site is published in English and Polish, so one source serves both language versions. The method is simple:
- The site reads the NBP table when it is built. If the service does not respond, it uses a saved fallback rate with its own date.
- The baht price is converted at the cross rate and rounded, so it reads as an estimate rather than a quote.
- The date of the rate is shown with the converted price.
Here is the same method applied to a round sum, chosen only as an example: THB 1,000,000 (about €26,000, NBP average rate of 23 October 2026).
None of this is the rate your bank will give you. Banks and payment providers add a margin to the mid-market rate, and the margin varies. Treat our estimate as a starting point for your own figures.
Currency risk on a staged payment schedule
Currency risk is the chance that the rate moves between the day you agree a baht price and the day you pay it. We do not say which way it will move. We only show the arithmetic.
At The Astra Samui, according to the developer: Payments: 30% by 20 December 2026, 30% when the roof structure is complete (planned for February 2028), 40% at handover (planned for December 2028). The developer does not offer financing.
So there are three payments, spread over about two years, and each one is converted at its own rate. Take the starting price as an illustration: the first 30% is THB 1,110,000, the second 30% the same, and the final 40% at handover is THB 1,480,000. Those baht amounts stay the same. The euros needed to cover them do not.
The arithmetic, in general terms: if between two payments the baht becomes 5% more expensive against the euro, that instalment costs about 5% more in euros. If the baht becomes 5% cheaper, it costs about 5% less. The baht price is the same in both cases.
Three things decide how much this matters to you:
- The size of the payment. The final instalment is the largest, and it comes last, when the most time has passed.
- Time. The longer the gap between agreeing the price and paying, the more room the rate has to move.
- The route. Converting twice (for example pounds to euros, then euros to baht) means two rates and two margins.
Our guide to buying an off-plan condo in Thailand explains how the payment stages link to construction.
Which currency to send
For foreign freehold there is a rule about where the money comes from. According to the developer: For foreign freehold, funds must come from abroad in a foreign currency (not Thai baht). The buyer pays any transfer charges.
In practice, you send euros (or your own currency) from an account abroad to the developer’s account in Thailand, and the receiving Thai bank converts them to baht. You do not convert to baht at home first. The Thai bank then issues the document that shows the money came from abroad, which you need at the Land Office when the title is transferred. Our FET form guide explains that document and what to write in the payment reference.
This has a consequence for the exchange rate: the conversion to baht happens at the Thai bank’s rate on the day the money arrives, not at your bank’s rate. If you hold pounds, dollars or Swiss francs, you can usually choose whether to send those directly or to convert to euros first. Ask both banks which route costs less.
Bank margins and transfer costs: what to ask
The real cost of moving money is more than the headline rate. It usually has three parts:
- the margin in the exchange rate, compared with the mid-market rate
- the fee for the international transfer
- fees charged by intermediary banks along the way, which can reduce the amount that arrives
As the rule above says, transfer charges are paid by the buyer. Questions to put to your bank or payment provider before the first instalment:
- What rate do you apply to a large international transfer, and how is it set on the day?
- What is your margin compared with the mid-market rate, and can it be negotiated for a large sum?
- Can I send euros so that euros arrive, without you converting them on the way?
- What fees do intermediary banks usually take on transfers to Thailand, and who pays them?
- Can I fix a rate in advance for a future instalment, and what does that cost?
- How long does the transfer take, and how will I know it has arrived in full?
Ask the same questions of any money transfer app you are considering, and check first that it can deliver the bank document the Land Office needs.
A worked example
Here is a simple illustration using the starting price. It is not a quote and not a forecast.
| Payment | Share | Amount in baht |
|---|---|---|
| First instalment | 30% | THB 1,110,000 |
| Second instalment, at roof structure | 30% | THB 1,110,000 |
| Final instalment, at handover | 40% | THB 1,480,000 |
| Total | 100% | THB 3,700,000 |
Now imagine three buyers with the same unit and the same baht price. The first converts each instalment on the day it is due. The second holds euros and sends them as each date comes. The third, with the money already set aside, asks the bank about fixing a rate for later payments. All three pay the same baht. They may pay different euro amounts, and none of them can know in advance who will pay least. The difference is in how much uncertainty each one accepts.
Remember the reservation fee as well: Reservation fee: THB 100,000 (studio, 1 bedroom or 1 bedroom plus) or THB 150,000 (2 bedrooms), fully refundable until 20 November 2026, 17:00.
Questions to ask before you pay
- Is every price and payment in my agreement stated in baht?
- Which currency will I send, and from which account?
- Will the receiving Thai bank convert the money, and at what rate?
- Which document will the Thai bank issue to show the money came from abroad?
- What is my bank’s margin and fee on this size of transfer?
- Who pays intermediary bank fees, and will the full amount arrive?
- How will I keep track of the rate and cost of each instalment for my own records?
If you are buying from the UK or elsewhere in Europe, tax and banking at home add their own questions; we cover them in separate country guides. For the steps from reservation to title, see how to buy. When you want to go through the numbers for a specific unit, book a call. We will give you the baht figures in writing, so you can check the conversion with your own bank.
Questions and answers
Can I pay for a Thai condo in euros?
You send euros, but the price is in baht. For foreign freehold the money has to arrive in Thailand in a foreign currency, and the receiving Thai bank converts it to baht. The baht amount in your contract does not change; the number of euros it takes depends on the exchange rate on the day.
How much is a price in baht worth in euros?
It depends on the day’s exchange rate, which changes every working day. This page shows the conversion at a dated NBP average rate as an estimate. Your bank will use its own rate, usually with a margin, so the amount you pay will differ.
What is currency risk when buying property in Thailand?
It is the chance that the exchange rate moves between the day you agree the baht price and the day you pay. If the baht strengthens against your currency, each payment costs more in your currency; if it weakens, less. With staged payments, each instalment has its own rate.
Do you forecast the baht exchange rate?
No. Nobody can tell you where the rate will go, and we do not try. We explain the mechanism and the questions to put to your bank or financial adviser.
Which exchange rate do you use on this site?
The National Bank of Poland (NBP) average rate from table A, used as a cross rate to euros and US dollars, with its date shown next to the estimate. If the NBP service is unavailable at build time, a saved fallback rate with its own date is used.
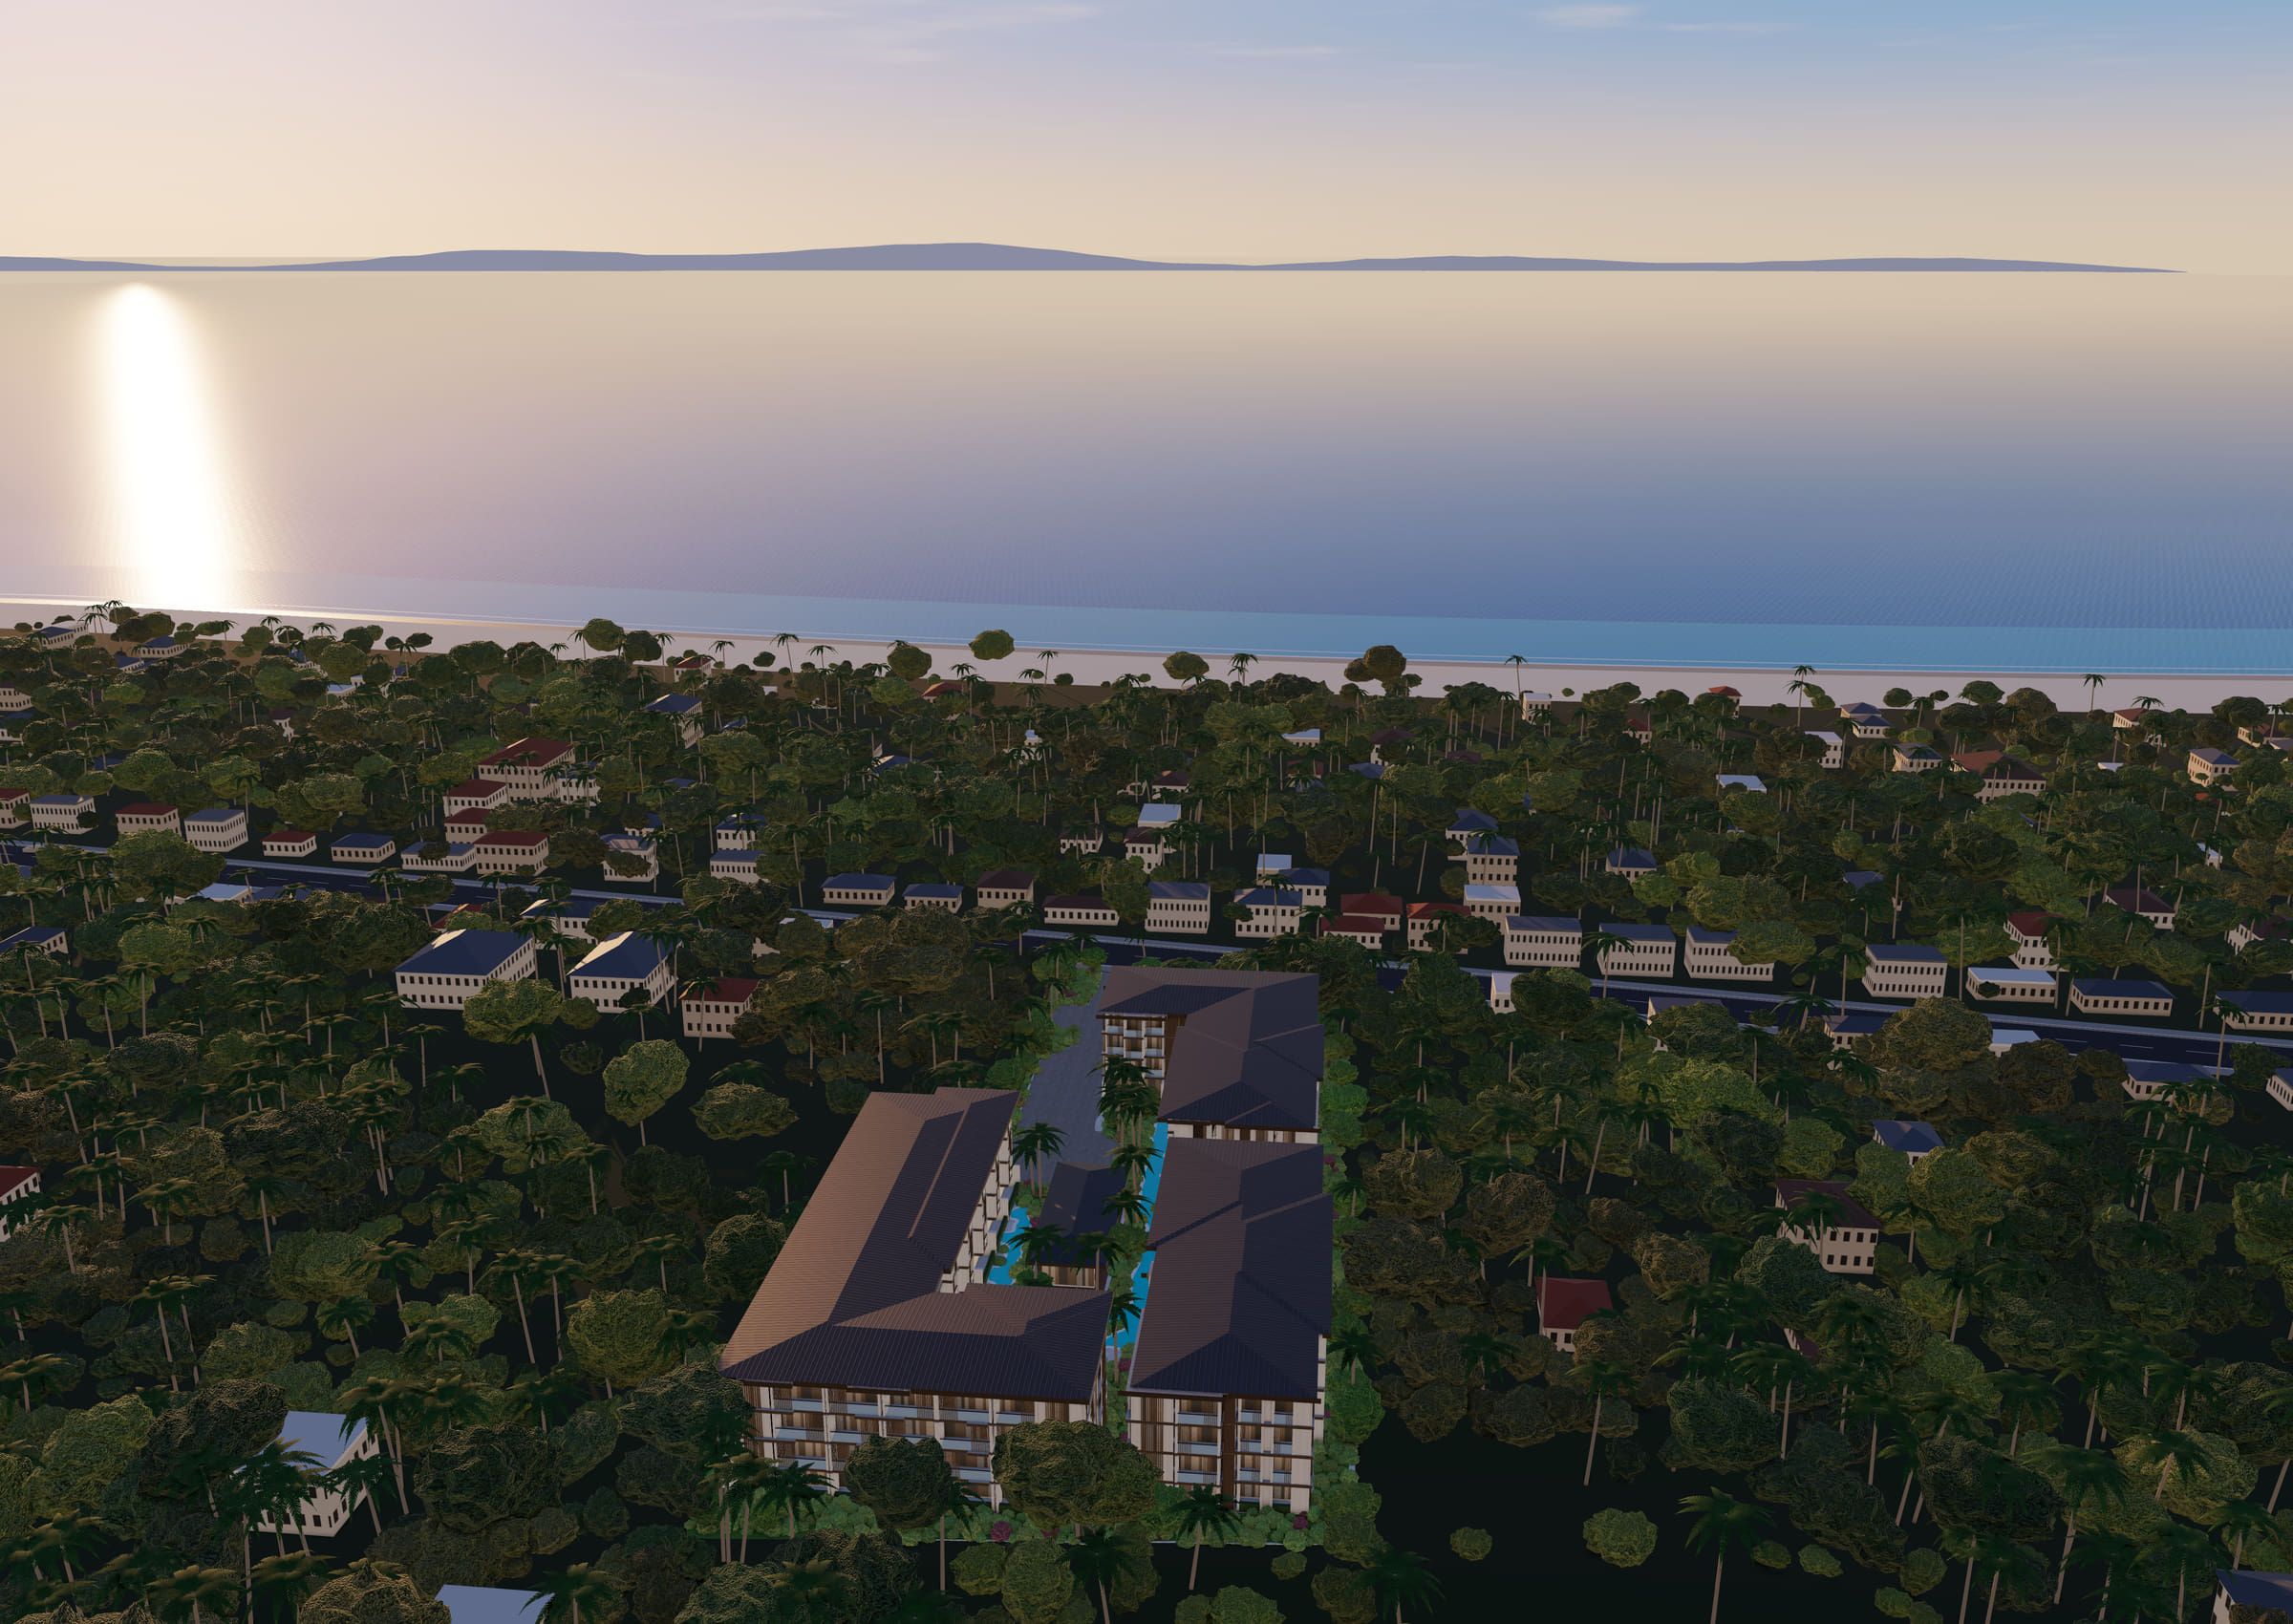
Choose your apartment in 3D
Open the 3D model of the development, pick a building and a floor, and see where each apartment sits and which way it faces.